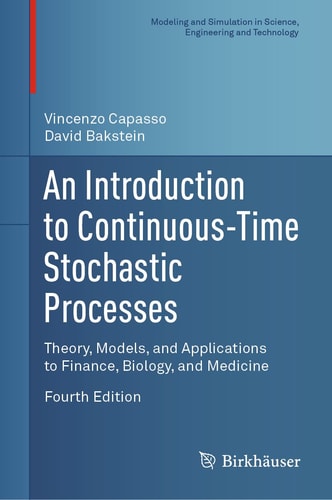
An Introduction to Continuous-Time Stochastic Processes Theory, Models, and Applications to Finance, Biology, and Medicine
Available copies (1)
| Price | Condition | |
|---|---|---|
| $76.47 | New |
Sold and shipped by Basi6 Direct. Stock and pricing refresh on page load.
About this book
This textbook, now in its fourth edition, offers a rigorous and self-contained introduction to the theory of continuous-time stochastic processes, stochastic integrals, and stochastic differential equations. Expertly balancing theory and applications, it features concrete examples of modeling real-world problems from biology, medicine, finance, and insurance using stochastic methods. No previous knowledge of stochastic processes is required. Unlike other books on stochastic methods that specialize in a specific field of applications, this volume examines the ways in which similar stochastic methods can be applied across different fields.
Beginning with the fundamentals of probability, the authors go on to introduce the theory of stochastic processes, the Itô Integral, and stochastic differential equations. The following chapters then explore stability, stationarity, and ergodicity. The second half of the book is dedicated to applications to a variety of fields, including finance, biology, and medicine. Some highlights of this fourth edition include a more rigorous introduction to Gaussian white noise, additional material on the stability of stochastic semigroups used in models of population dynamics and epidemic systems, and the expansion of methods of analysis of one-dimensional stochastic differential equations.
An Introduction to Continuous-Time Stochastic Processes, Fourth Edition is intended for graduate students taking an introductory course on stochastic processes, applied probability, stochastic calculus, mathematical finance, or mathematical biology. Prerequisites include knowledge of calculus and some analysis; exposure to probability would be helpful but not required since the necessary fundamentals of measure and integration are provided. Researchers and practitioners in mathematical finance, biomathematics, biotechnology, and engineering will also find this volume to be of interest, particularlythe applications explored in the second half of the book.
Details
Categories
Mathematics, Probability & Statistics, Stochastic Processes, Business & Economics